

Welcome Avatar! It looks like we can come to a few conclusions from the last week. The most important one we’ve already addressed in the paid side of the stack numerous times. Big picture is that AI is unable to jump from cost saving to revenue generating. It is absolutely unbelievable that it is able to do Wall Street (Associate/Analyst work) in 1/100th the amount of time. Honestly, mind boggling.
That said, if you ask AI about a business idea, you can convince it to sell: 1) dresses to adult men, 2) feces in a box from various animals and 3) status lowering goods for women. The craziest one is actually the last one as it is blasphemy for the 80%+ of all consumer purchases.
Anyway. When the costs continued to pile up and revenues did not match, the AI investments started to look like a bunch of hype with little substance. Which leads us to the current time.
Quick Lead Up
Paid stack readers already knew this was the expectation. That said, the reminder for what has happened: 1) debt kept piling up at hyperscalers and other AI/Datacenter companies, 2) interest rates started to go up making new issue debt creep into high singles and even teens for some companies, 3) MSFT/OpenAI/Anthropic and other companies started to virtue signal around slowing AI for “good of humanity”, 4) OpenAI and Anthropic missed their private revenue bogeys that investors had expected for growth and 5) we now see the Jensen is out of NVDA and the circular financing loop that started this hockey stick is hitting and ugly speed bump.
That brings us to November 16.
As of November 16 - Circular Money Dries Up
One of the main causes of the huge exponential growth of chip sales is the circular financing that was created by NVDA. The goal (with Jensen out) seems to be simple: make him take the blame for the whole thing. The affairs are really not relevant and the Company wants a scapegoat for clicking pause to the circular financing flywheel.
What was Happening in Simple Terms
NVDA was directly giving money to AI companies and AI/Data Center Providers. They were made as equity investments.
Once the Company receives the money they commit to purchasing a certain amount of NVDA systems
This allows the companies to build up the infrastructure before generating enough revenue/profit to justify all the builds
As these companies generate revenue/profit at a quicker rate than usual a chunk of this money goes back to buying GPUs as well. Therefore you have multiple items juicing NVDA sales: 1) NVDA itself buying stakes in companies, 2) the bigger capacity allowing for more GPU purchases and 3) capacity allowing more debt financing in general
Another wrinkle in this is that NVDA is on the hook for unsold capactiy out several years, example being 2032 capacity for CoreWeave
Raising money and getting outside investors is a lot easier with guaranteed contracts (price of stock booms)
Eventually the economics of AI need to make sense. Paying $100 a month for an AI subscription that is gross margin negative is not viable long-term
Undoing this Loop
Sounds good on paper. Essentially NVDA can put $1B in to a company, they end up selling a bunch of GPUs and the price of the customer stock goes up because they have a guaranteed allocation and investment from NVDA. NVDA wins by a wide margin as long as the customer makes money off the much bigger amount of capacity.
We’re basically watching this work in reverse because of the following:
Interest rates went up significantly, debt markets no longer writing these checks without seeing results from the prior builds
End user demand is not profitable as of today, just look at Anthropic S-1
If NVDA is forced to stop writing these Equity checks for period in time the flywheel gets an Emergency Brake pulled on it
There is also risk that capacity/demand dries up if AI companies need to raise prices to show profitability and revenue does not show up from all of this AI integration for the end customer (enterprise or even individual)
Jensen Out Adds More Complications
We’re not going to bother with the opinion side. Just look at the reality of the situation. A lot of these deals were made through him and because of him. His relationships with the customers and his willingness to take equity stakes.
With him out of the picture it’ll at least cause a pause.
Current investors will question adding to NVDA positions without a CEO they know and trust
NVDA will slow down these Equity Grants until they have made an official solution to their CEO hunt
Interest rates are not coming down which means less debt financing is available
Add in some hysteria around security/doom stuff all over X and investors get even more cautious
End result, hate him or love him, a slow down in terms of the fly wheel/financing loop. Instead of juicing the revenue up faster by a 3x, it’s going to go back to a standard Purchase/Sale agreement in the interim.
Scapegoat: As this doom loop continues, the most likely position for NVDA is to blame Jensen as the reason for the slowdown in AI. In addition to that, the employees that could have quit years ago are going to be incentivized to leave. California non-competes are practically useless out there (every state is different and California non-competes are pretty weak at best).
Where It Leaves Us Now
Now that it is explained out we can give some basic simplified ways to think about it below:
Data Centers are being built well ahead of revenue. There is no guarantee that all the capacity will be used to generate real profits for the end user
A lot of of the customers are actually realizing that the AI is not able to generate revenue, (outstanding at cutting costs like back office/number crunching)
Major companies like MSFT and other Software entities want AI to slow. Smart individuals are making their own optimized spread sheets and QuickBooks
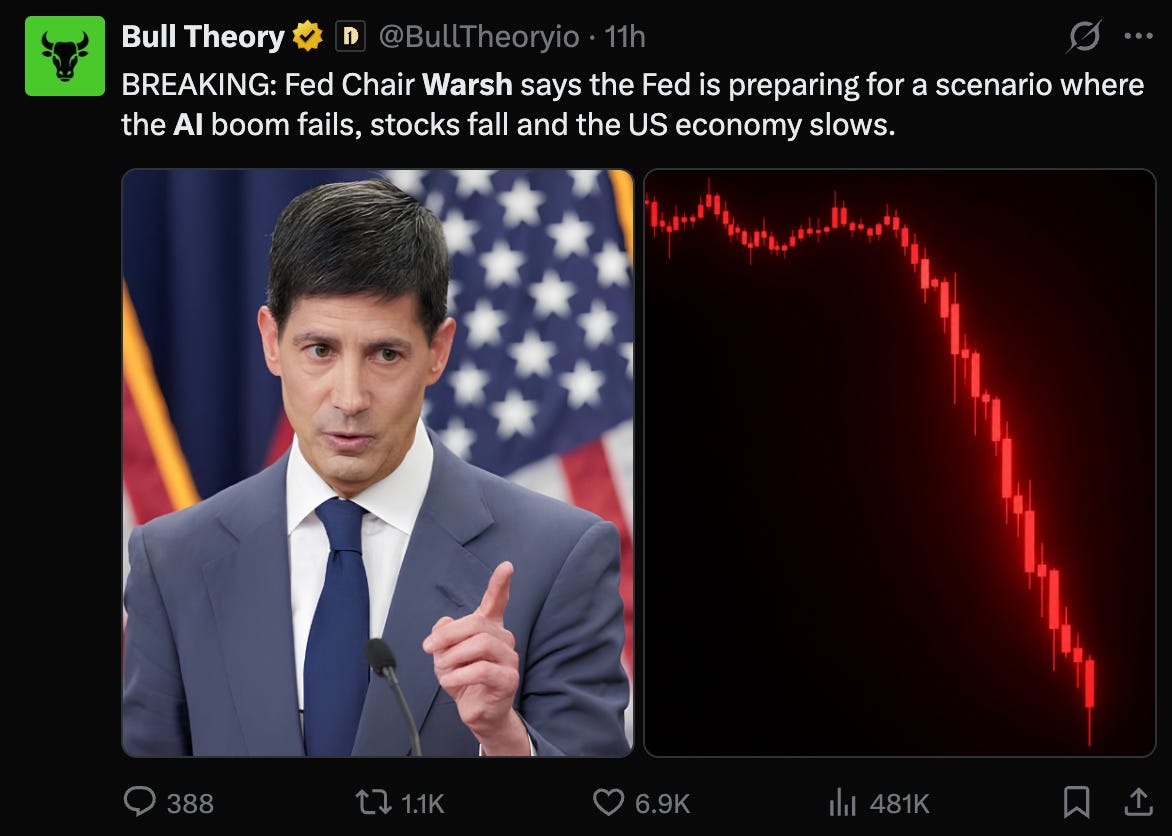
Now we’re seeing talks of an AI slowdown at the government level
Signs to Look For
This is the general explainer (from our perspective of course). If you want to look for signs you would expect to see the following:
More conservative/slowing revenue guidance from NVDA and the customer base
Smaller companies seeing severe financial weakness and perhaps going under from over leverage and no bailout backup (can’t call Jensen for money offset by equity)
Recent cyber security issues being entirely blamed on AI to justify a massive slowdown in the data center build out
Luckily we don’t have to wait long for this to play out. Whopping 3 months.
In the interim, everyone has forgotten that there is a digial asset that hasn’t been hacked. But don’t worry, freezing up Chase/Wells Fargo is just a blimp for them to collect that interest spread by “halting withdrawals”
Disclaimer: None of this is to be deemed legal or financial advice of any kind. These are *opinions* written by an anonymous group of Ex-Wall Street Tech Bankers and software engineers who moved into affiliate marketing and e-commerce.
Old Books: Are available by clicking here for paid subs. Don’t support scammers selling our old stuff
How ETH is Staked: Covered (here)
Crypto: The DeFi Team built a full course on crypto that will get you up to speed (Click Here)
Crypto Taxes: We have a suggested Tax Partner and 25% discount code, for information see this post.
Security: Our official views on how to store Crypto correctly (Click Here)
Social Media: Check out our Instagram in case we get banned for lifestyle type stuff. Twitter will be for money