

Welcome Avatar! Several Jungle natives have created 7-8 figure brands at this point. With that in mind we think it’s a good time to give you a clean explainer for why Entrepreneurs end up over investing. This is the inverted problem of frugality (barely save enough to live a cheap life).
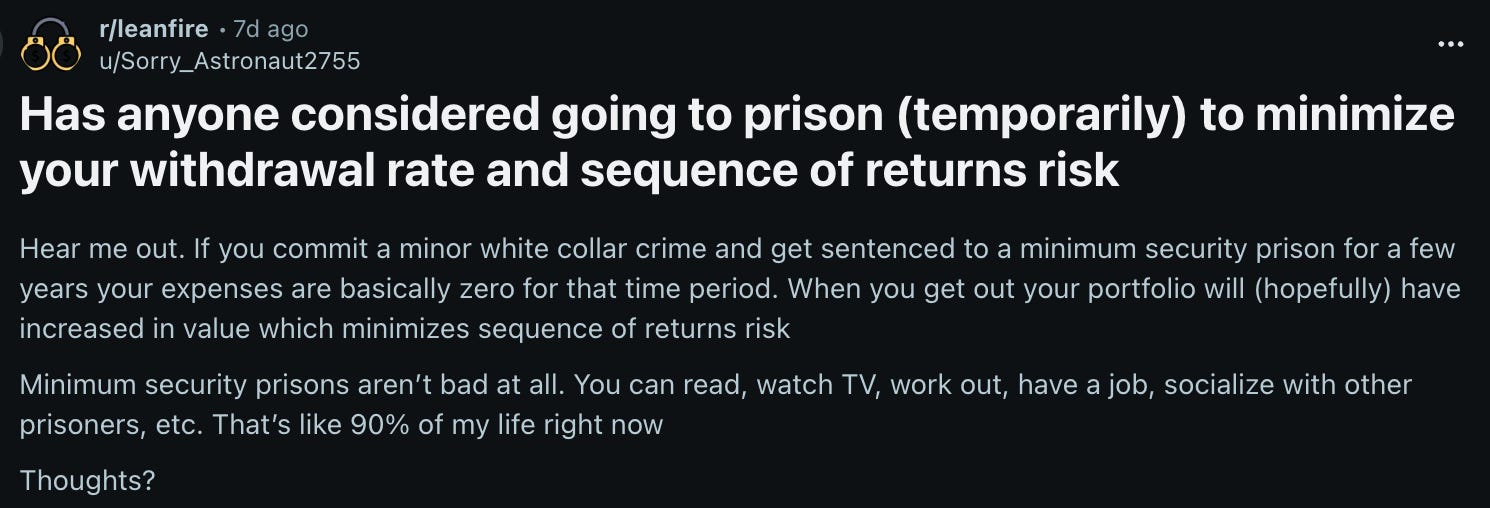
Frugal people try to cut costs to zero and even consider crime to lower their costs (quite literally a perfect post below).
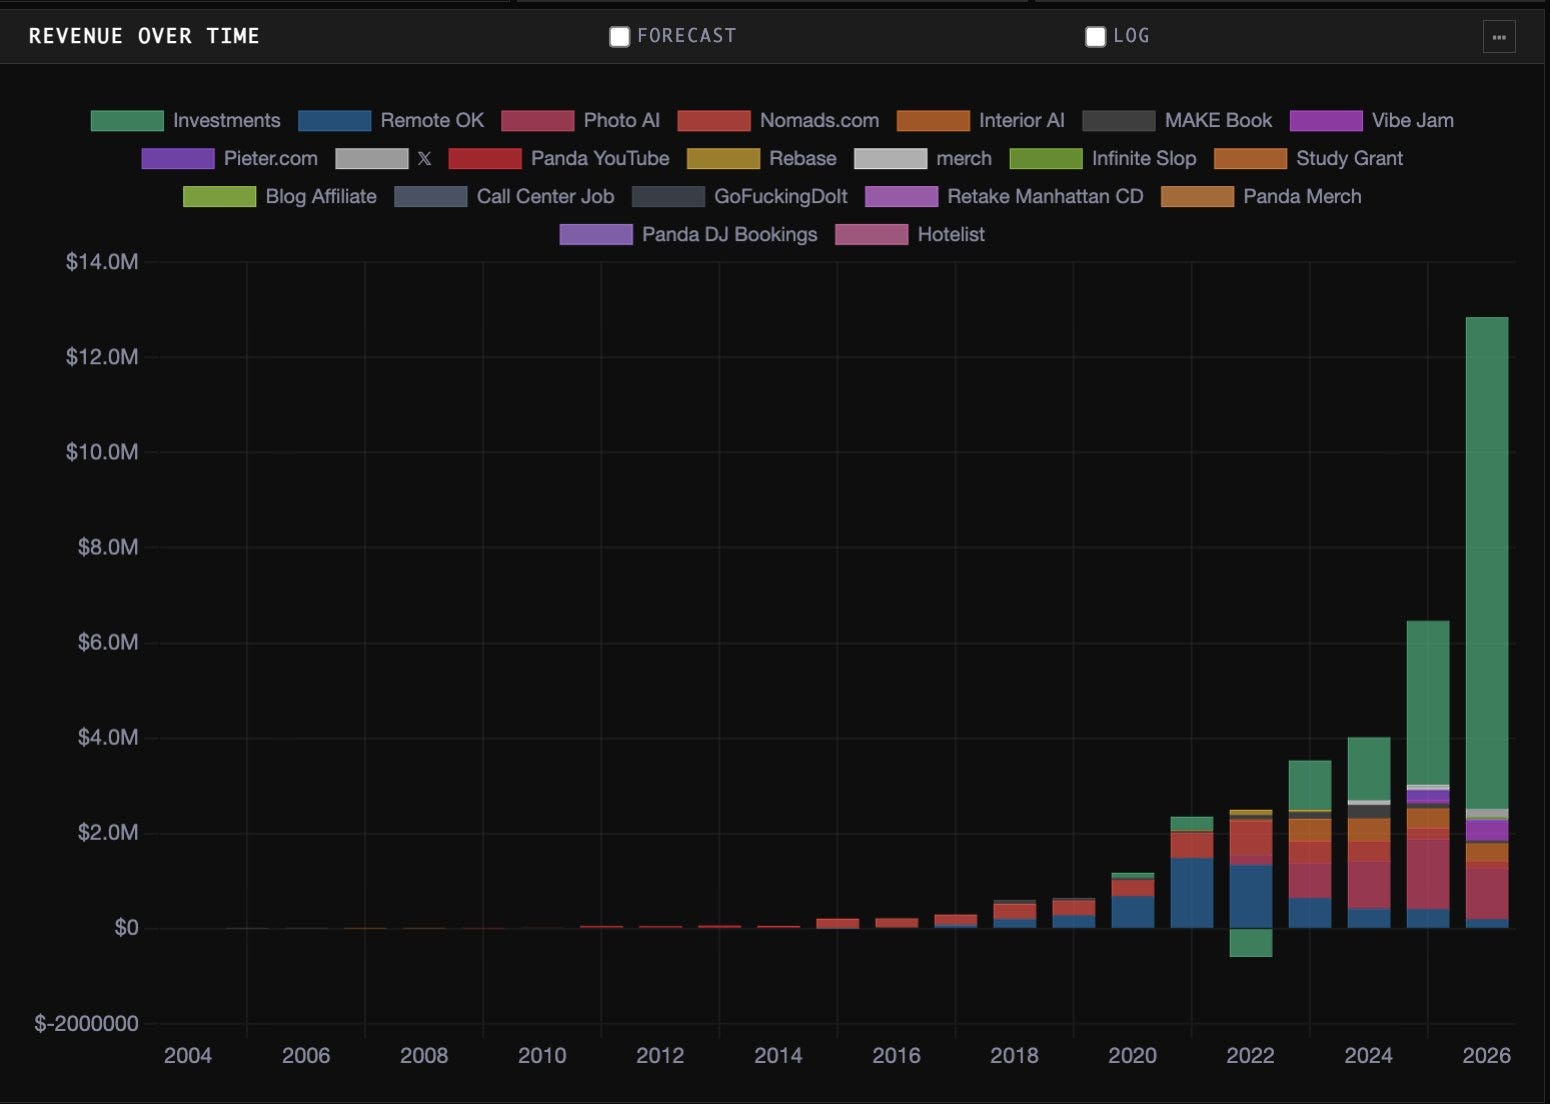
Entrepreneur types end up investing like it’s a 5-alarm fire only to wake up in 10 years and realize their investments move the needle more than their income streams.
Chart from Levelsio on X App
Why You’ll Over Invest - Psychology
The most important part is actually the psychology of it. Everyone ignores this stuff despite it being the most important. Getting wealthy via WiFI money requires a certain level of glass eating and sh*t sandwiches. You get out of the tunnel (rough average of 3-years depending on skill/talent/luck) and end up in a state of anxiety and confusion.
For years you lived under the belief that you were going to lose it all. You were going to be a billionaire. And. Back to the down month which makes you think you’re going to lose it all.
If you worked for 3-years straight and went through the worst pain of your life, would you go spend it on a Super Car? Nope. No one does. They end up investing it hard. The only people who make this type of brain dead decision = fast money payout (sudden influx of wealth vs. the standard 3-year hazing ritual). 99% of people won’t fall in that category.
You have nothing in common with normal people after succeeding with your first venture. You may have soft contacts with W-2 workers and other high income individuals. However, your thought process and day to day lives drift. By the time you’re out of Shawshank you’re on the other side of the Grand Canyon
Everyone hopes you will fail. You learned this during the grind. This makes you 10x more paranoid that they might be right
You’ve also read millions of horror stories of people losing it all after one bad year
End result? You end up shoving every penny you can into investments. This becomes a major habit that impacts you later as the muscle is hard to turn off.
Why You Over Invest is Also a Function of Lifestyle
Every Entrepreneur has an absolute hatred for being told what to do. This runs deep into the DNA of the individual. While you see glimpses of this vibe within a high pressure industry (Wall Street, Tech etc.), the people are still playing the game which suggests it’s still bearable to them.
The intensity in corporate is tied to scarcity vs. productivity. Completely different mentalities although they look the same from the outside. Hyper intense because you don’t want to leave a penny behind (promotion/raise etc) is not the same as distain for hierarchy.
Typical Lifestyle Cost Complaints Don’t Pertain to You
People claim that they understand how rich people operate. They know a few high earning MDs on Wall Street or they know a few successful tech/sales people. This is great but it’s still not the same lifestyle as an Entrepreneur. Being an entrepreneur allows you to control your time (if done correctly) which completely changes all of your decisions. Quite literally all of them.
Example: We’ve posted about kids several times and will continue to do so. It is a night and day comparison. If someone works an ultra high stress career, they have no real time with them.
The real child raising is done by nannies, day care facilities and private schools. Not joking one bit.
Compare that to someone who controls their own schedule and the entire lifestyle is flipped on its head. Why would you pay for a day care or nannies when all you really need is a few hours a day to get important tasks done? This line of thinking isn’t even talked about because it is so rare. Hence the eventual disconnection from the majority.
Lifestyle Inflation Issues Shrink as Well: As a rule of thumb, the typical person will spend about 2.5x as much as they did at 25 compared when they are 50 (inflation adjusted already).
This means if someone spends $50,000 at age 25 they would spend about $125,000 at age 50 ***inflation adjusted*** which would probably be around $261,000 (assumes 3% inflation).
At this point it levels off and declines a tad after 65 at a rate of about 2%. (Source on consumption and Source on slow decline later in life)
Big problem. Is your spending really going to ratchet up like the upper class workers? Highly unlikely (hint living it). Unless you have a serious problem to deal with, it’s a lot easier to proactively use your time to solve problems. This becomes quite humorous if you read between the lines.
There is no real need for tutors, landscapers (tent cleaning) or paying for meal prep. While you will go out to eat, you become extremely conscious of what you are consuming for the health of the entire family. End result? Costs don’t scale as much as you were told when compared to the drinking, traveling and general adventure in your 20s/early 30s.
Re-Enter Psychology
This comes back. Again. You survive a few more years but the above has been smashed into your brain for years. Everything gets “soooo much harder” and “sooo much more expensive”. You end up planning for the armageddon scenario that doesn’t show up.
Click open on the crypto wallets, the brokerage accounts and suddenly… you’re way further ahead than you thought you would be.
The biggest tell that you’re way further ahead than you thought? Starting a family has no impact on the “need to make more money” button in your brain. You don’t have any anxiety or panic, you simply move through the sleep deprived nights like it’s another busy day for the Company (for about 6 months).
When This Cross Over Happens
We’ve written (forever) that you’ll need to give up about 3-years of horrifying work ethic to make it. The second part of this we can go ahead and reveal now as we have enough data points
~9 years after you start making real money, the investments will matter more than your income.
Just like the 3-year number, the average here is exactly that. An average. There are exceptions to the rule where someone makes a killer investment and is catapulted to a new level. There are also people who squander it investing into a litany of bad investments.
New Issues Come In: At this point you have three massive psychological events taking place at once. First, you realize you will not spend the money. Second you realize that you are less valuable than your assets. And. Third, you realize that continuous learning is the only way you will create sustainable generational wealth within your family.
#1 Can’t Spend It: Blah Blah 4% rule Blah Blah. Doesn’t even matter. Anyone who is first generation rich (looking at YOU) is the talented person. Given a gift of suffering + persistence and decently high IQ.
This means you have spent ~12 years getting wealthy and the chances of you doing nothing is near zero. You have too much value and people will clamor for your attention allowing you to make enough money to offset living expenses (bare minimum). The doom of being completely redundant is low at this point (unless you are in an industry that is being replaced entirely ie. Blackberry or Blockbuster).
#2 You vs. Your Decisions: At this point, your decisions matter more than your effort. If you’re generating more net worth from your investments it means those decisions deserve more of your attention than your day to day work. The irony is in part 3…
#3 Have to Stay Ahead: The reason your investments were good and you were able to get to this position in the first place is that your work consistently integrated new tech/different angles. Guess what that means? Working is already part of your investment process. In fact, if you stop working you won’t be a great investor because you won’t be on the ground floor anymore. This is also why you constantly see us testing (and losing money at times) with new ads/platforms etc. If something works, we know it and invest in it!
As You Can See Lady Luck Follows You For Life
Lady luck only goes for result agnostic individuals. She has no interest in lazy people either. She has an interest in people who laugh in the face of disaster/distress and continue to put the work in no matter what life throws at them. The Mike Tyson punches are humorous only because they are so predictable.
People who think they hit their number and do nothing? Ultra thin chance that is you (enter worthless exception to the rule MySpace guy story or random streamer).
Instead the real payoff is you get to control your time. If you hit your number and loathe what you do? Sure go ahead and quit. Thing is we know (already) you’ll be doing something else within about 6-9 months. You earned the right to work on something you enjoy but the chances you choose nothing is razor thin.
In an exciting twist of fate. Since the idea will not matter to you and it will be enjoyable, Lady Luck typically shows up again. Right when you are fully over invested and don’t care if it works out. Funny how that happens.
End With a Little Trolling for the Winners
Since a lot of you are in this process right now, think it’s a good time to do some quick calculations. This assumes you run a healthy business that just grows with the market.
Go ahead and look at your current net worth. Assume that investment gains are 3-4% above inflation (even S&P does this so it’s not a wild assumption). Now add in the income you’re generating (as a percent of net worth). This is your real return.
3-4% + Added Savings = Real Return.
Since you are selling a product that matches inflation (in general) that means this is a good rough proxy
Compound that for 10-15 years.
Let us know what you see.
We already know what it says. You will be sitting on a pile of digits with nowhere to go.
Summary
It’s absolutely great to have a “number”. This is because it removes excuses for doing things you hate. When you hit your number and run three WiFi businesses while loathing one of them? Sell it.
The “number” is essentially a clean removal of excuses. Only do the things you enjoy or make adjustments to them to create enjoyment (maybe you just spend a bit more to avoid tasks you hate).
Instinctively, we all know this. A person with real wealth is not going to spend his time complaining about work or where he lives. If he was actually rich he’d just move to where he is happy or quit the company/job
If you are worried about not having enough or having saved too much, we’re going to wager on the latter. IF you pay the price to escape the W-2 environment.
Even though you read this post, you’re going to over shoot it anyway.
Happens to everyone who makes it.
Cap it.
Disclaimer: None of this is to be deemed legal or financial advice of any kind. These are *opinions* written by an anonymous group of Ex-Wall Street Tech Bankers and software engineers who moved into affiliate marketing and e-commerce.
Old Books: Are available by clicking here for paid subs. Don’t support scammers selling our old stuff
How ETH is Staked: Covered (here)
Crypto: The DeFi Team built a full course on crypto that will get you up to speed (Click Here)
Crypto Taxes: We have a suggested Tax Partner and 25% discount code, for information see this post.
Security: Our official views on how to store Crypto correctly (Click Here)
Social Media: Check out our Instagram in case we get banned for lifestyle type stuff. Twitter will be for money