

Welcome Avatar! Completely different post style today. Has been a long time since we did something like this and it’ll be useful for people looking ahead into middle age. Also useful for anyone in this general ball park.
Considering that the average life span is about 80 years (no need to BS us about living forever), that would leave as roughly middle age. If you’re close to 40 you’ll see a lot of these things in your day to day and if you’re younger, it’ll be something to plan for.
#1 “Kids Are Expensive”
This only applies to people who have kids. We’re not in the camp to demand that everyone has them. Lots of people would make terrible parents and don’t have the capacity nor capabilities to be a good parent. There are a multitude of other real reasons to remain childless. However. Extending your partying years to travel and mess around makes little sense (as you’ll see later in this post).
What actually happens? Unless you have a large number of kids, your financial situation won’t change much outside of housing. Assuming you could already afford a 3 bedroom place, having 2 kids will not change your numbers *that* much. Instead your spending just shifts.
When you’re single your expenses are actually pretty big on discretionary spending:
Flying to new places every month or two to see the world isn’t free. (Montreal, Tokyo, Iceland, and a million others all cost money). That also assumes you’re good at solving the code (how the city works) to avoid wasting money on places like Baltimore which has a small speckle that is enjoyable.
As you get older, dates, partying and all of that goes up. Don’t really have time to do the whole game/money debate that was argued for 20 years now. Attractive people have options so you have to present yourself as a good option. No one cares if you’re broke at 21. Everyone cares if you’re broke and 35
Dry Cleaning, eating out a ton. As you get older you lose track of the thousands you’re spending on changing wardrobes, new outfits, constant parties/theme parties and new $200 a person restaurants. All this adds up
When You have Two Kids:
All of your expenses simply shift. Instead of spending on alcohol and flights that becomes diapers, kids shoes, kids events and likely a house cleaner to free up your time
Your food costs actually go down because you naturally start eating healthier. Don’t want to give a child food from a random restaurant all the time. Ends up being a couple times a week just to take a break and the kids will make it an event anyway
Expenses do ratchet up with activities, however, by this time your fixed costs are likely eaten up by inflation anyway. If you have lived in a house for 5-10 years, the mortgage cost vs. your income is pretty light
The TL;DR here is that money isn’t an excuse for anyone successful. You spend a metric ton of money partying and going out if you were a successful person anyway. If you want to be a good parent, your priorities change and that’s that. The one expensive balloon payment is probably “college” in quotes since most of you will likely teach them WiFi money/entrepreneurship. Funding a UTMA, 529 and Trump account is going to be fine with regular contributions
#2 - You Have a Lot Of Time
Absolutely false. By the time you get to middle age all the major life events happen. You will see people who failed miserably, people in corporate for life, people who get a life changing illness and people who made tens of millions. In addition to the financial side there is a wide range of personal life changes. Moving to new cities, families, etc.
During all this commotion you learn that life is actually quite short. If someone is 40 years old today, you can estimate that four out of five of them will make it to 70. That’s the rough math under the assumption that they already made it to 40!
This means every person you know, the 5th one, is not going to make it to 70. People love to cut data to make it seem rosy, however, stick with the general picture and that’s what you get (actuary data has about 83% living to 70 if they already made it to 40)
If you want some good data on this, you can check the actuarial life table here: (source).
Hard to Read the Summation, however, Exiting your 40s and you’ve got ~30 years.


#3 - Income is Stable
The main problem with W-2 (as we’ve beaten to death for years), is that people assume it is safe. This is because wage increases are high in 20s and even early 30s. After that the vast majority of people do not make it up the corporate ladder. This is simple math.
If there is one regional manager, there is only one seat. That person is not going to leave it for as long as he can. Also. As soon as someone younger and cheaper comes along, he will be cut. As long as revenue is the same/similar, the company is always looking for the best way to reduce costs.
We’ve seen a lot of people both talented and not so talented fall victim to company changes. It’s basically Russian Roulette. If you’re extremely good but work at the wrong firm or wrong department, you’re gone. Someone can be mediocre and simply work at the right company and survive for a full career. Crapshoot.
While Everyone Wants to be on the Hockey Stick, It Doesn’t show for how long!
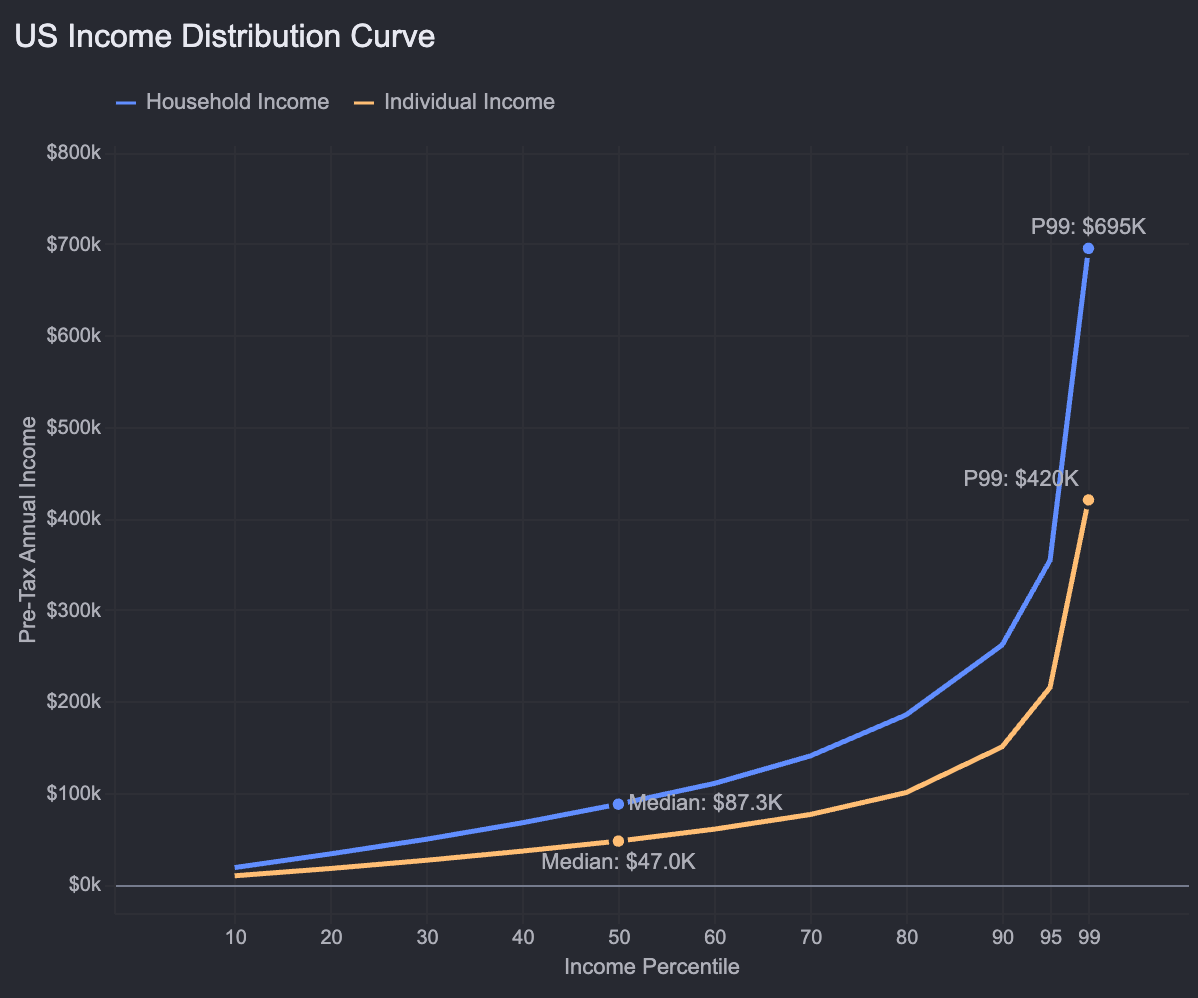
To put this in perspective, 11-12% of people in the USA will actually earn top 1% income for at least one year in their life. This does not mean they do it consistently for decades. Something to remember in the year when you feel like you’re on top of the world (Mike Tyson around the corner).
#4 - You’re Forever Young
We’ve written about this relentlessly. Unless you were always out of shape, there is a steep drop off in middle age for all performance metrics. Don’t care if you were a lifter, sprinter, cyclist, basketball player, baseball player etc. You will simply feel it when it shows up.
This actually causes severe issues if you try to “get it back like the old days”
Pain is signal at this age cohort. It means you are forced to dramatically change exercise routines. Gone are the days of heavy lifting and 5 mile runs while hungover.
The quick and simple set up looks like this
3 days a week of weights, legs at least 2 days a week. Use dumbbells for single leg work and avoiding heavy squats/deadlifts. Abuse kettlebells and indian clubs for strength + mobility combo
You must stretch every single day and do some mobility. No excuses. 10-15 minutes. Your chassis tightens. This means those tendons and ligaments are trying to go into bad posture due to laziness. Without the flexibility and constant mobility you will look terrible and move terrible if neglected. We failed on this topic and should have started at 30. Paying the price but it is fixable in middle age
2-3 days of golf/tennis/cardio. Some combo. Tennis is basically the best longevity game since it naturally forces more flexibility + stretching + mobility. Toss in some zone 2 swimming/biking/hiit for 20-25 mins and you’re set
1-2 days rest depending on how you feel
Always go longer on the days you feel good. If your body is clicking do the extra reps/sets etc. Just take the next day off. It will be obvious when you’re feeling good vs. bad. Do not press through pain/stiffness it’ll make things worse
#5 - “Earnings Are What Matter”
If you have played the game of life correctly (in general), you will learn that your investments matter just as much (if not more) than your earnings by this age. Again. This assumes you played it right.
To do some quick math, if you shoot for a 10% return think about how much a 2% swing is.
$1M? It is about $20,000 in each direction
$5M? It is a $100,000 swing in either direction
$10M? It is a $200,000 swing in each direction
Include the low capital gains tax for long-term holdings. You can quickly recognize that $100,000 in long-term cap gains is worth a metric ton more than a W-2.
To be clear on this, you’re still going to work because you still have more than enough energy to grind it out. The problem is that it doesn’t make a ton of sense (like it did in your 20s). If you burned the candle on both ends at age 25, adding $25,000-$50,000 to the net worth was likely a huge percentage. By the time you’re in middle age, adding $50,000 unlikely means much. On $5,000,000 it is just one percent. Better to just keep hours reasonable and focus more time investing.
TL;DR around middle age you want investment returns to beat your annual earnings. This is also why the first $4M is always the hardest
The First $4M is the Hardest

Welcome Avatar! We’re going to make the argument that the first $4M is the hardest. About 25-30 years ago it was “the first million is the hardest”. The problem is that $1M now and $1M back then buy completely different assets. Make no mistake, a million bucks takes effort, the path to $4M is simply a different level for the majority.
#6 - Avoid Comparisons in Middle Age (Big Time)
It’s pretty natural to compare. People do this as they have egos and want to be the best of the best. The problem with this strategy? By middle age there are too many factors at play.
As mentioned a trillion life events happen. Now you’ve got people who made it by themselves. Some people got a huge trust fund cliff. Super star employees get axed and take a 50%+ reduction in pay. Some people over-lever on mortgages. Other people go live in a low COL area and completely drop off the radar.
In general the cliche of running your own race is true. Just ask yourself if your younger self (5-10 years ago) would be impressed with what you’ve built. Chances are high the answer is yes. That’s the easiest way to keep your eyes on the prize.
Oh. And. Never quit.
Tons of people simply give up. This ends up being market share, growth and opportunities for you. Stay in the game, keep working and lady luck eventually shows up. As long as you’re keeping momentum, the probabilities are in your favor.
#7 - Random Money Stuff
If you want the biggest mistakes people make (we didn’t make these) it is as follows.
Do not buy stuff that will own you. If you buy too much house or go down the path of car loans + leverage… you will create a prison for yourself. Do not assume that everyone around you is rich. They might be rich. They might be levered up with nothing but a house to their net worth. It doesn’t matter. The goal is to avoid fixed costs that cannot be easily swapped out.
Create an investing system. Similar to people who juggle 15 different projects and wonder why they never succeed… they don’t have a clear plan. You should have a strategy at this point. If you are saving $10,000 or $1,000,000. That money should be ear marked to a specific strategy fit for you
You are underspending on saving time. Chances are high that you should be outsourcing chores. The main one we think everyone should have? A weekly or bi-weekly cleaner. Having the house organized and avoiding that entire process is massive. Practically get an entire day back and you can focus on work or hanging out with friends/family
You are overspending on materials. By the time you’re in this band, you don’t need to showcase wealth anymore. Everyone already knows you’re doing well based on where you live anyway. No need to dress like a slob. However. Spending as much as you did when single makes little sense
Go ahead and keep the high-end gym. The contacts and ecosystem alone will make sure you’re always in the know when it comes to new things in the area
#8 - Random Non-Money Stuff
Most people think of rich families and assume that they outsource the child care to private schools and nannies. That’s a cool stereotype. Doesn’t need to be your reality.
Unless you’re selfish or narcissistic, you’re not going to be interested in having other people do the family oriented activities. We’ve found the entire discourse on social media to be comical (at best). There is absolutely nothing difficult about raising a kid exclusive of the first 6-9 months of bad sleep schedules (that part does suck).
The right way to do it is to get your WiFi money up and step into the active role. Do not buy into the massive BS about it being the hardest job in the world. It is equivalent to any basic role you’ve had at age 20-26 working for a company. Compared to running a company and starting one from scratch it registers a 2/10 on the scale.
“What’s the payoff” there is no financial payoff **gasps**. The payoff is that your own kids love you to death and go to you for everything.
This seems to bother people (that there is no financial payoff). We don’t understand that logic because the money is just going to go back to the government if someone is child-free and rich. At this point life isn’t a spreadsheet (and shouldn’t be)
#9 - Disaster Planning
This is another big change. We don’t write about it too much but you essentially optimize away from disasters. This means: 1) umbrella insurance, 2) walking more vs. driving, 3) trust funds/UTMA/accounts not in your name and 4) skipping high risk activities like riding motorcycles
We’re well aware that the fourth one makes people feel old. That’s fine. You’ll see if you decide to have kids. The last thing you want to do is end up in a wheelchair with two kids age 7 and 10. Will be a traumatizing experience for them as well. And. Shocking surprise, you’re not the most important person in the family unit anymore!
No matter what we write, we know that the majority won’t listen. This is obvious because we see people getting injured in adult league soccer, basketball, football and MMA events on a monthly basis. If you have to do it, you have to do it. We’ll go ahead and stick with tennis, golf and individual cardio/lifts. Tearing an ACL or patellar tendon is not something we’re interested in.
The odd thing about disaster planning is that the majority of it no longer relates to money. You start asking yourself how your kids survive if you’re hit in a freak car accident and they are under 18 years old. Ugly stuff. Something to organize and plan for ASAP
#10 - You Become a Morning Person
This is ultra strange for natural night owls. If you’re a night person, you end up taking a nap in the middle of the day to make the hours line up. Yes. Seriously. It’s a lot better like this because you maximize your hours with the family.
Once the kids are in school (private, public, homeschool (example), we don’t care what you choose), there is a period of time for you to catch up on sleep. It’s an interesting way to maximize work output as well.
Generally speaking you wake up, hit the gym, do all the kid stuff, send to school, work, take a nap, pickup kids for all activities, then work again while they are sleeping and repeat.
The typical move for most people is to simply go to sleep early and wake up early. If you’re a true night owl, you end up doing what we described above.
#11 - Stimulants/PEDs don’t work as Well. Forced into Diet
We’ve written quite a bit about HRT and other such items on the paid side (Source). That said, it is important to note that the results won’t be as strong. Getting older simply means things don’t work as well as they used to.
This applies to everything by the way: caffeine, peptides, TRT/HRT, microdosing. You name it.
If you can read between the lines, it also means your diet becomes more important. The days of constantly eating pizza, fried chicken, random candy bars and other unhealthy foods are dying off.
You will be forced into a new diet. We don’t know what your adjustment will be. Ours was much more food based (eating out too much) and yours might relate to cycling stimulants. Since the stimulants don’t work as well as they did before, you need large periods of zero stimulants. This resets all the receptors so when you really need it, you can use it.
The TL;DR here is inflammation and weight gain will show up. If you know of this in advance you’ll catch it when the scale starts reading more than usual. Actually on that note, you should probably get a scale and just weight yourself 1x a week when you wake up. Track it next to your journal and you’ll catch any issues.
#12 - Imbalances and Other Health Stuff
Everyone knows of the standard colonoscopy and annual blood tests. This is beyond that. You probably want to do a few other things: 1) Dexa scan, 2) calcium heart scan and 3) see an eye doctor even if you’re in good health
From years of sitting and grinding on that computer, you probably have some muscle imbalances. You want to fix this over time and check for a 10% or greater imbalance on one side vs. another. Your dominant arm/leg is likely going to be slightly stronger but you don’t want a real imbalance. This causes the body to tear and break down faster
Calcium heart scan is basic for anyone who has a history of heart disease. Even with no disease in the family tree, get it checked. You lose nothing and might catch a cardiac issue early which is worth millions
Eye sight begins to decline, most will be into reading glasses territory when they are at the tail end of middle age. Try to keep that one together as long as possible since you’ll be playing golf and tennis anyway (if you’re smart!)
There you have it some good and bad about getting older.
The Good: Kids aren’t as expensive as people make them seem. Your health quality goes up since you don’t want them eating awful stuff. Your investments outpace your earnings and you typically have a lot more time freedom.
The Bad: The health related risks ratchet up quickly. You don’t want to be tied to a W-2 because this is where it is just as risky to run your own thing vs. working in a mega company who hopes to fire you. You’re also much less athletic/strong/mobile and there is nothing you can do about it.
Bonus: You will find a lot of new interests if you have kids. Your kids will develop interests in things you never heard of and since they like it you will like it as well. It is 100x more rewarding than partying and hooking up for the 7,000th time at a new city.
On that note, back to the tent!
Disclaimer: None of this is to be deemed legal or financial advice of any kind. These are *opinions* written by an anonymous group of Ex-Wall Street Tech Bankers and software engineers who moved into affiliate marketing and e-commerce.
Old Books: Are available by clicking here for paid subs. Don’t support scammers selling our old stuff
How ETH is Staked: Covered (here)
Crypto: The DeFi Team built a full course on crypto that will get you up to speed (Click Here)
Crypto Taxes: We have a suggested Tax Partner and 25% discount code, for information see this post.
Security: Our official views on how to store Crypto correctly (Click Here)
Social Media: Check out our Instagram in case we get banned for lifestyle type stuff. Twitter will be for money